Home Loan Eligibility for a ₹1.4 Crore Flat in Bangalore
Featured Image of Home Loan Eligibility for a ₹1.4 Crore Flat in Bangalore


Home loan eligibility for a ₹1.4 crore flat in Bangalore starts with one number. Banks fund up to 75% of the value, so your loan comes to about ₹1.05 crore. At 7.5% for 20 years, the EMI is about ₹84,600 a month. To get that approved, you need a net monthly salary of about ₹1.7 lakh, with no other loans. A longer 30-year tenure cuts the EMI to about ₹73,400 and the salary need to about ₹1.47 lakh. Your own cash outlay, including taxes and fees, will run above ₹50 lakh.
How Much Loan Will a Bank Give on a ₹1.4 Crore Flat?


RBI rules cap the loan-to-value ratio by loan size. For loans above ₹75 lakh, a bank can fund only 75% of the property value. The rest must come from you.

Item Amount
Flat price ₹1.4 crore
Maximum loan at 75% ₹1.05 crore
Your down payment ₹35 lakh

Banks also leave out stamp duty and registration from the value they fund. So you pay those from your own savings.

EMI for a ₹1.05 Crore Home Loan


Home loan rates in November 2026 start around 7.5% for strong profiles. SBI's rates range from about 7.5% to 8.7%, based on your credit score and profile. Here is your EMI at three tenures and two rates.

Tenure EMI at 7.5% EMI at 8.5%
20 years ₹84,587 ₹91,121
25 years ₹77,594 ₹84,549
30 years ₹73,418 ₹80,736

A 1% rise in the rate adds about ₹6,500 to your monthly EMI over 20 years. So lock in the best rate your credit score allows.

Salary Needed for a ₹1.4 Crore Flat


Banks check your fixed obligation to income ratio, or FOIR. This is the share of your net income that goes to all EMIs. Most lenders allow 40% to 50% for salaried buyers.

Tenure Net salary at 50% FOIR Net salary at 40% FOIR
20 years at 7.5% ₹1.69 lakh ₹2.11 lakh
25 years at 7.5% ₹1.55 lakh ₹1.94 lakh
30 years at 7.5% ₹1.47 lakh ₹1.84 lakh
20 years at 8.5% ₹1.82 lakh ₹2.28 lakh

These figures apply when you have no other EMIs. A car loan of ₹20,000 a month raises your salary need by ₹40,000 at a 50% FOIR. So clear small loans and credit card dues before you apply.

Total Cash You Need Beyond the Loan


The down payment is only the start. Under-construction flats carry GST, and every sale deed carries stamp duty and registration.

Cost Rate Amount on ₹1.4 crore
Down payment 25% ₹35 lakh
GST 5% ₹7 lakh
Stamp duty, registration and cess 7.6% ₹10.64 lakh
Total own cash About ₹52.6 lakh

Karnataka doubled its registration fee from 1% to 2% in August 2025. That change alone adds ₹1.4 lakh on this flat. Also check the cost sheet for parking, club, legal and power charges. If these sit outside the base price, add them to your cash plan.

Five Ways to Raise Your Eligibility


If your salary falls short, you still have options.

  • Add a co-applicant, such as your spouse or a working parent who co-owns the home.
  • Pick a longer tenure, which lowers the EMI and the salary needed.
  • Close or prepay small loans to free up your FOIR.
  • Push your credit score above 750, and ideally above 800.
  • Show extra income, like rent or a regular bonus, with proper records.

Age matters too. Many banks want the loan repaid by about age 70. So a buyer at 30 can take a 30-year loan. A buyer at 50 may get only 20 years.

How Construction-Linked Payments Help


For an under-construction flat, the bank does not release the full loan at once. It pays the developer in stages as construction moves ahead. During this time, you pay only pre-EMI, which is interest on the amount released.

This eases your cash flow in the early years. Full EMIs begin once the bank releases the whole loan or when you choose to start them. Starting full EMIs early reduces your total interest, so consider it if your budget allows.

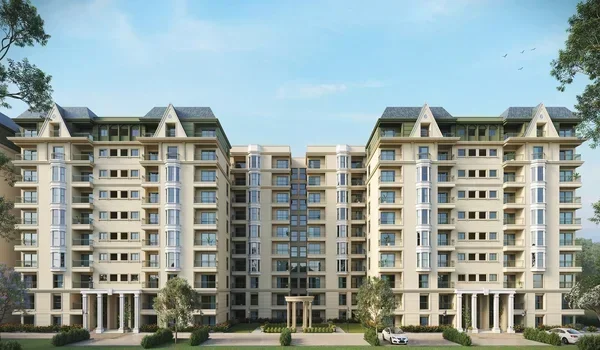
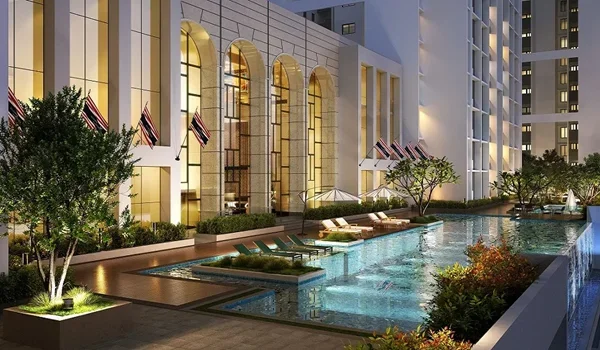
A ₹1.4 Crore Home at Prestige Falcon City Reserve


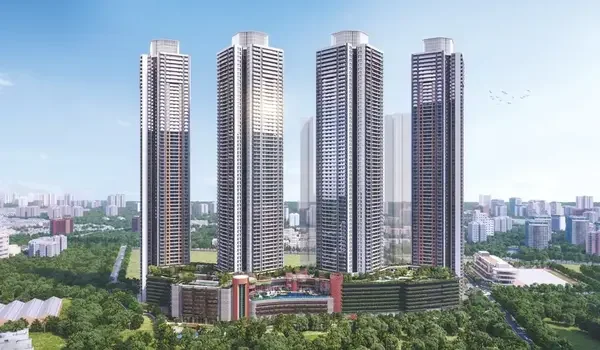
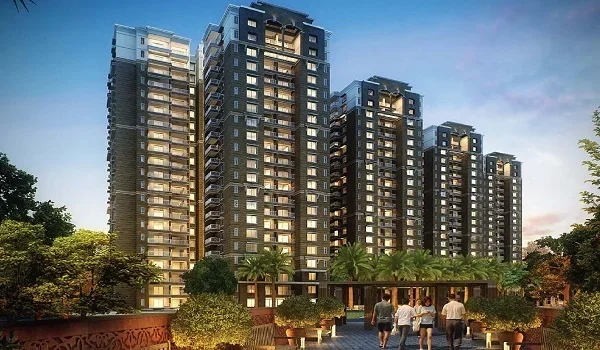
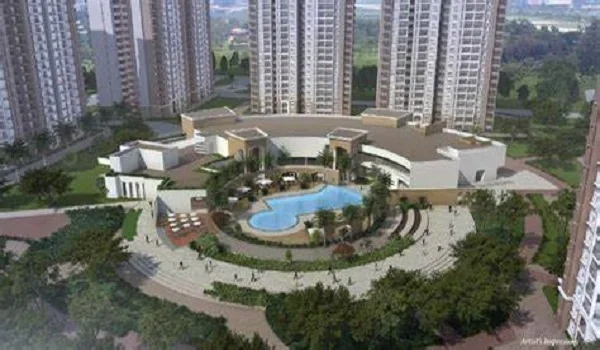
The ₹1.4 crore budget matches the starting price of 2 BHK homes at Prestige Falcon City Reserve. These homes measure 1,240 to 1,379 sq ft on super built-up area. The project is a new phase of the 41-acre Prestige Falcon City township on Kanakapura Main Road.

SBI, HDFC Bank, ICICI Bank and Axis Bank provide home loans for the project. The payment plan follows 10% at booking, 10% at agreement and 80% in construction-linked stages. So your loan releases match the work done on site, and pre-EMI stays low in the first years.

The location also supports the loan math. The project sits opposite Konanakunte Cross metro station, and Forum South Bengaluru lies next door. Homes near a working metro line tend to rent well and resell faster. That gives you a safety net if your plans change before the loan ends.

Quick Eligibility Check Before You Book


Take your net monthly salary and halve it. Subtract any current EMIs. If the balance is above ₹85,000, you can likely service a ₹1.05 crore loan over 20 years. If it is above ₹74,000, a 30-year loan should work. Then ask two banks for a sanction letter before you sign the agreement.

FAQs


1. What salary do I need for a ₹1.4 crore flat in Bangalore?

You need a net salary of about ₹1.7 lakh a month for a 20-year loan at 7.5%. With a 30-year tenure, about ₹1.47 lakh works, if you have no other EMIs.

2. What is the EMI for a ₹1 crore home loan?

At 7.5% for 20 years, the EMI on ₹1 crore is about ₹80,600. On a ₹1.05 crore loan for a ₹1.4 crore flat, it rises to about ₹84,600.

3. How much down payment do I need for a ₹1.4 crore flat?

You need at least ₹35 lakh, since banks fund only 75% above ₹75 lakh. Add GST and stamp duty, and your own cash rises to about ₹52.6 lakh.

4. Can I get a 90% home loan on a ₹1.4 crore property?

No. RBI rules allow 90% only on loans up to ₹30 lakh. For loans above ₹75 lakh, the cap is 75% of the property value.
5. Does a co-applicant increase home loan eligibility?

Yes. Banks add the co-applicant's income to yours when they check FOIR. A working spouse can often raise your eligible loan by 50% or more.

6. Is Prestige Falcon City Reserve approved by banks for home loans?

Yes. SBI, HDFC Bank, ICICI Bank and Axis Bank provide home loans for the project. Compare their rates and fees before you choose one.

Prestige Falcon City Reserve Blog


Enquiry
Enquire Now